IRS Form 12153 · Collection Due Process
The IRS form that opens a Collection Due Process hearing.
Form 12153 is free to file — and it starts a 30-day clock. The hearing that follows is where cases are won or lost. If you're holding an IRS levy or lien notice, the window has already opened.
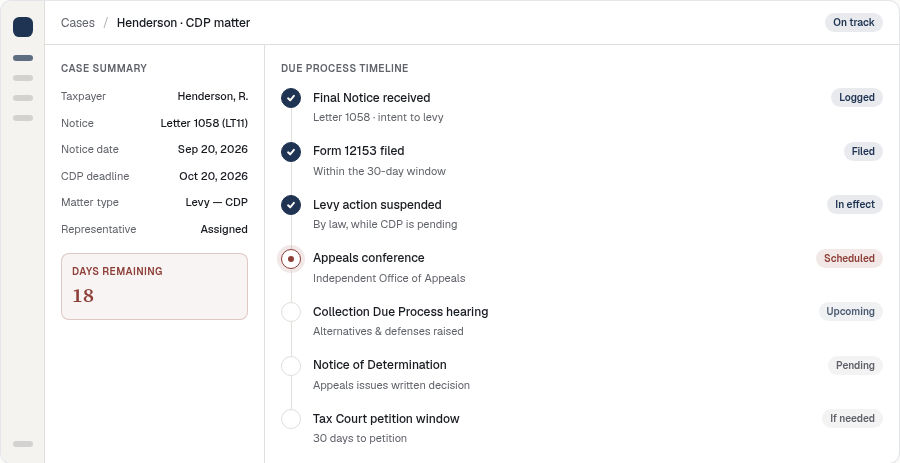
Illustrative overview of the Collection Due Process stages a levy notice sets in motion — from the Final Notice through an Appeals determination and, if needed, Tax Court.
Definition
Form 12153 is the IRS form a taxpayer files to request a Collection Due Process (CDP) hearing or an Equivalent Hearing with the IRS Independent Office of Appeals after receiving a Notice of Intent to Levy or a Notice of Federal Tax Lien filing. Filed within 30 days, it suspends IRS levy action and preserves the right to petition the U.S. Tax Court.
Authorized under Circular 230
Calculus Tax is authorized to represent clients in all tax matters before the IRS — Los Angeles, CA, since 2013.
Not affiliated with the IRS
A private tax representation firm. We charge for the hearing, not the free form.
Your information stays private
Notices and details you share are used only to review your case and contact you.
Why you got this form
The IRS has moved your account from sending notices to taking enforcement action.
A Final Notice of Intent to Levy or a Notice of Federal Tax Lien filing is not another reminder — it is the step that unlocks levies on wages and bank accounts and secures the government's claim against your property. Form 12153 is how you pull that decision in front of the independent IRS Office of Appeals before it happens.
The 30-day clock
For levy notices, the deadline is 30 days from the date printed on the notice. Miss it and the strongest protections fall away.
See every deadline by notice type →CDP or Equivalent — the difference is not small
File within 30 days and you get a Collection Due Process hearing: levies are suspended by law, the collection statute is tolled, and you keep the right to Tax Court. File late and an Equivalent Hearing is usually the most that remains — an Appeals conference without those protections.
What a hearing can actually do
A CDP hearing is not just a pause. Appeals is required by law to do specific things, and a well-prepared taxpayer can put specific issues on the table.
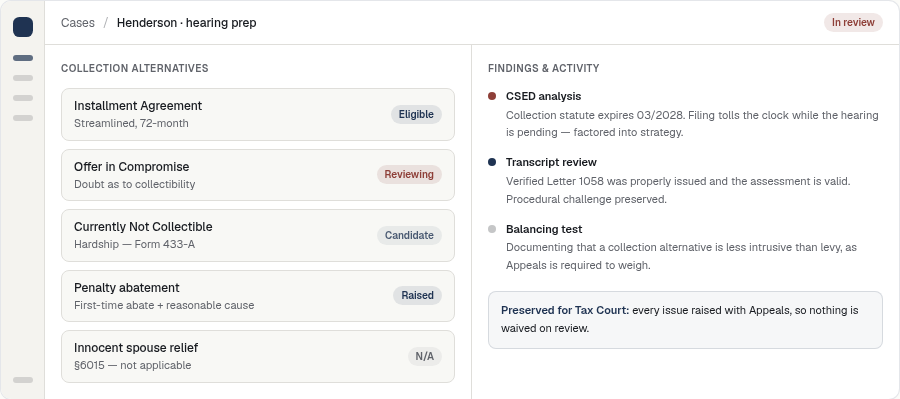
Illustrative view of how a hearing is prepared — weighing collection alternatives, verifying the notice and statute, and preserving every issue for review.
What a CDP hearing can do
Verification, liability challenges, collection alternatives, the balancing test.
The 10-year collection clock
When filing helps — and when it quietly hands the IRS more time.
Your passport
A pending CDP request can block passport certification.
Penalties & abatement
FTF/FTP, the Trust Fund Recovery Penalty, interest abatement.
Lien hearings
Withdrawal, subordination, and discharge of a federal tax lien.
Tax Court after CDP
The 30-day petition window and abuse-of-discretion review.
Why representation matters
Filing the form is the easy part. The outcome turns on what happens next: reading the account transcripts, deciding whether the CSED helps or hurts, choosing the right collection alternative, raising liability and procedural defenses correctly, and preserving every issue for Tax Court.
Issues you don't raise with Appeals generally can't be raised later. That is why the hearing — not the form — is what you pay a representative for.
Did a tax relief company charge you thousands to “file a CDP”?
Form 12153 costs nothing to file, and filing it only opens a hearing — it does not settle or close your case. If your firm filed the form, went quiet, and your balance hasn't moved, you may have paid for a form, not a result.
Frequently asked questions
Straight answers to what people ask when a levy or lien notice arrives.
- Form 12153 is the IRS form a taxpayer files to request a Collection Due Process (CDP) hearing or an Equivalent Hearing with the IRS Independent Office of Appeals after receiving a Notice of Intent to Levy or a Notice of Federal Tax Lien filing.